All Categories
Featured
Essential Part D Enrollment Tips in Next Year
Table of Contents
Like all health insurance, receiving in-network care is best to keep your out-of-pocket expenses low. However, unlike HMO plans that won't cover any portion of your bill if you seek out-of-network care (except in a covered emergency), you can get out-of-network care when traveling out of your routine strategy network area with a PPO policy.
Insurance in Vista CACost-conscious people should consider a couple of drawbacks to PPO plans that may make getting care more expensive. While they're versatile and convenient, PPO strategies have greater premiums.

If you do have a deductible, it's likely to be more expensive than other plan types. While your insurer will share the cost with you, you'll likely pay a higher coinsurance percentage for out-of-network companies. When you visit an in-network company, they'll file your claim to your medical insurance company on your behalf.
PPO insurance policy holders may discover the claim filing procedure made complex if they're not utilized to it or time-consuming if they regularly need out-of-network care from a professional. In 2023, the typical annual premium for a group PPO strategy was $8,906 for self-only coverage and $25,228 for family coverage2. Companies contributed $7,399 toward a self-only plan, and staff members contributed $1,507.
Low-Cost Plan Choices for Veterans
The typical deductible for PPO plans was $1,281. As pointed out above, PPO plans purchased on the ACA markets likewise have a maximum out-of-pocket limitation of $9,450 for self-only protection and $18,900 for household plans. To sum up how HMO and PPO strategies differ, take a look at our fast chart. Self-only protection: $8,203 Family coverage: $23,758 Self-only coverage: $8,906 Household protection: $25,228 For 2024 ACA market plans, the optimum limit is $9,450 for self-only protection and $18,900 for family coverage.
Yes No Yes No Some plans do. Many strategies do. Whether you have an HMO or PPO plan, you can leverage a health repayment arrangement (HRA) to lower out-of-pocket medical expenditures.
Insurance in Vista CAOnly companies can release and contribute towards an HRA. Companies use an HRA to give their employees a month-to-month allowance to spend for medical expenses. As soon as an employee buys a qualified item or service, they submit paperwork revealing proof of purchase, and their employer reimburses them approximately their allowance amount.
Why Term Life Protects Future Wealth
Staff member reimbursements will be tax-free if their specific health strategy offers minimum necessary coverage (MEC). Companies can reimburse staff members for out-of-pocket expenditures and health insurance coverage premiums, including those for an HMO or PPO strategy. Individual coverage HRA (ICHRA): An ICHRA is likewise a stand-alone HRA, but it's offered to companies of all sizes and has no contribution limits.
They need to have a qualifying type of specific health coverage to participate. (GCHRA): Likewise understood as an integrated HRA, a GCHRA is for companies of any size who use a group health plan. Only employees enrolled in their company's group plan can take part.
While they have no maximum contribution limits, the IRS doesn't allow reimbursements for regular monthly premiums. No matter whether it's used in coordination with an HMO or PPO strategy, there's an HRA that can help employees spend for their out-of-pocket medical costs and, often, their health insurance premiums. An HRA is a popular alternative option over standard health benefits due to the fact that they're economical for employers and flexible enough for every single staff member.
Comparing PPO Network Flexibility versus Costs
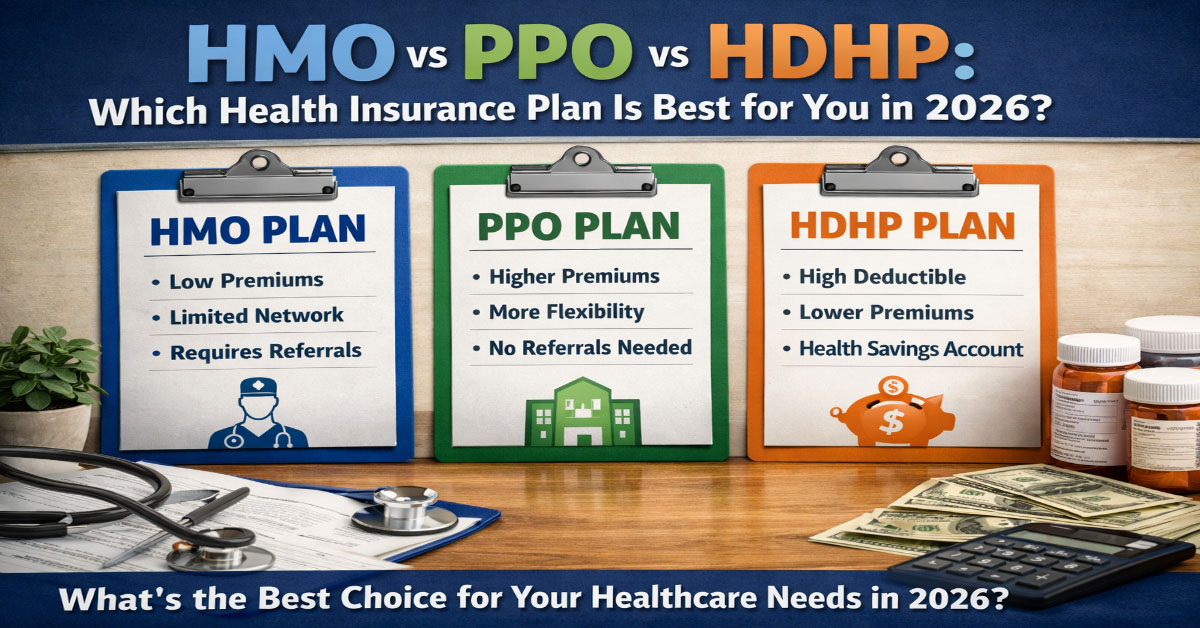
An HMO might be your finest bet if you're looking for a strategy with a low premium. Nevertheless, a PPO strategy offers extra versatility if you need more control over your healthcare. That's why investigating these plans carefully, including their pros, cons, and typical expenses, is the finest primary step you can take in the past deciding.
(MEC). (ICHRA): An ICHRA is also a stand-alone HRA, however it's readily available to companies of all sizes and has no contribution limits.
They should have a certifying form of specific health protection to participate. Employers can set various allowances based upon staff member classes for included personalization. Group coverage HRA (GCHRA): Also referred to as an incorporated HRA, a GCHRA is for companies of any size who use a group health insurance. Only employees enrolled in their company's group strategy can participate.
Reviewing 2026 Medicare Supplement Options
While they have no optimum contribution limitations, the internal revenue service does not allow repayments for monthly premiums. No matter whether it's used in coordination with an HMO or PPO plan, there's an HRA that can help staff members pay for their out-of-pocket medical expenses and, often, their health insurance coverage premiums. An HRA is a popular alternative option over standard health advantages since they're economical for employers and flexible enough for every single worker.
An HMO might be your best choice if you're looking for a strategy with a low premium. A PPO strategy supplies extra flexibility if you require more control over your healthcare. That's why investigating these plans thoroughly, including their pros, cons, and typical costs, is the very best primary step you can take in the past deciding.

Latest Posts
Selecting the Top 2026 Medicare Supplement Coverage

Understanding PPO and HMO Medical Plans
Deciding Between PPO Vs HMO Health Plans