All Categories
Featured

Comparing Family Health Quotes
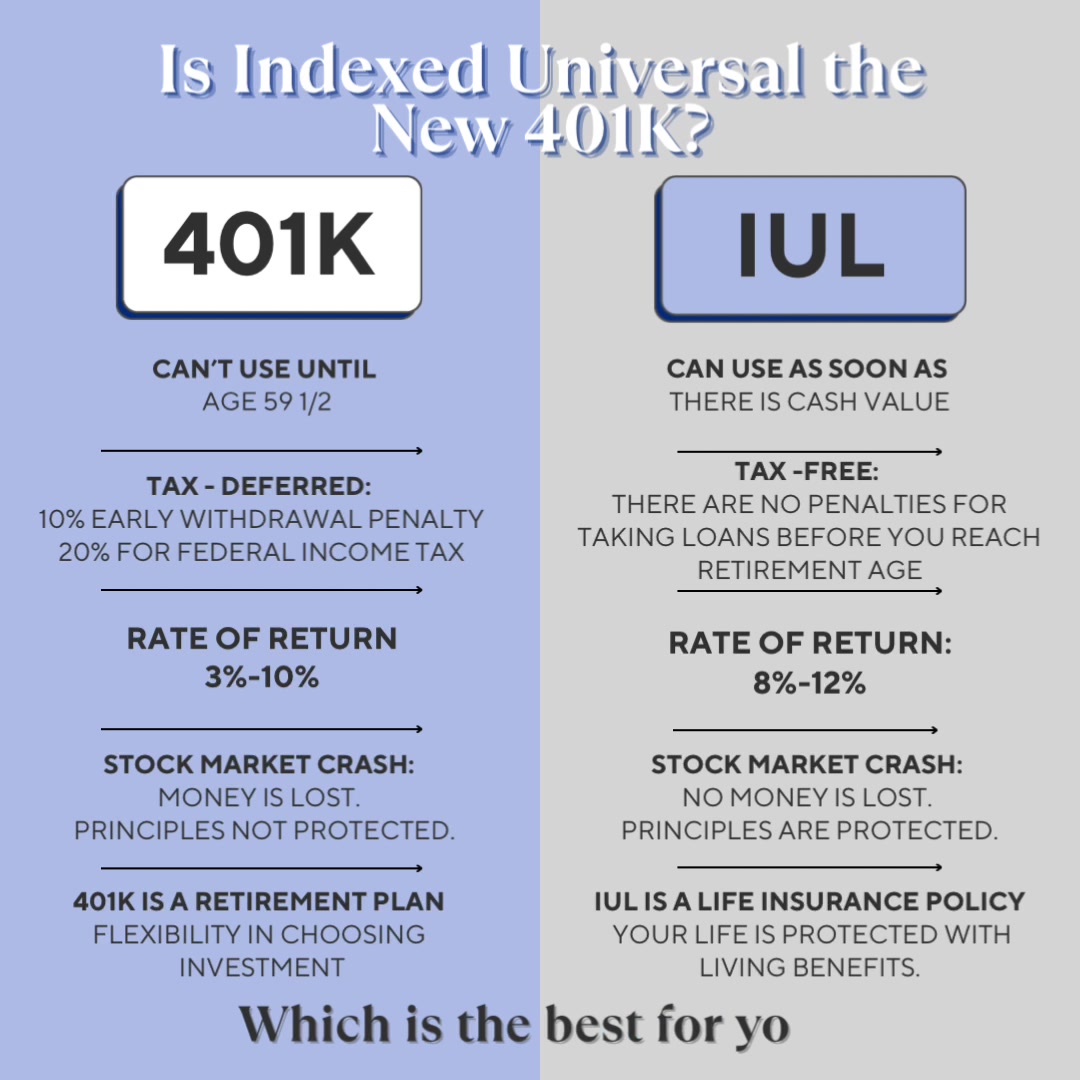
These exact same Indexed Universal Life products will considerably underperform if they're light funded and/or their efficiency does not have. That suggests that the internal cost load baked into the item is greater than it ought to be, and heavily based on efficiency to outrun the costs. These improperly developed items that get offered to the unwary masses are the factor you often hear IUL is an ongoing combination of debits and credits, so it's sensible to know what both sides of the journal appear like.
It's quite standard these days for many IUL policies to have some sort of getting involved loan choice, where your cash value still has market direct exposure even while borrowing versus it for emergencies or chances. Also, it's smart to think about the spread in between whatever the loan rate is and the cap so you understand what kind of positive arbitrage you can expect in bullish years.
So, having an integrated mechanism to record this prospective arbitrage will be vital in selecting the best-performing IUL policy. There are IUL calculators to help you figure out if you can expect long-term favorable arbitrage on your cash worth over various timeframes throughout bull and bearishness. Very same age, exact same ranking, Same premiumDifferent business, Various designs, Radically various cash valuesSee how your policy stacks up.
For these factors,, who is staying abreast of this quickly altering market and can notify you to the most recent news and opportunities. It's not unexpected that Penn Mutual ranks the highest of the finest IUL companies in regards to assurances considering that they likewise offer the best-performing Whole Life policy, a product understood for its guarantees.
Several of Penn Mutual's indexed accounts come with an ensured 1% flooring, which implies that even in down market years, you earn interest to balance out the ongoing cost of the death advantage. In spite of this 1% flooring, Penn Mutual still provides competitive caps on its S&P 500 strategies. Unlike the other best IUL business on this list, Penn Mutual does NOT provide Volatility Control Index strategies.
Financial Advice for Veterans
(In case you missed it above, VCIs are algorithmic market timing methods handled by widely known investment banks with high internal expenses and an absence of openness). Competitive Caps on the S&P 500 (sometimes with a 1% flooring instead of 0%)The capability to raise your S&P 500 cap (for an extra cost or spread of around 3%)Uncapped S&P 500 crediting techniques for maximum growthWith Penn Mutual's contractually locked 6% policy loan rate for the life of its IUL policy, you can keep your cash worth operating in the S&P 500 Index even while borrowing against it for emergency situations or outdoors financial investment chances.
Allianz occurs to be the only on the list and a foreign stock business at that. It's valid to fret that a German parent business might not have obligation to American policyholders if economic times get tough, however others like the fact a foreign stock business has differed sources of profits in varied insurance markets.
This permits them to offer their "rate lock feature," where IUL policy owners can freeze whatever gains they have at any point throughout the year. It's worth noting that you can just do this with their various volatility control indexes (VCIs) and not the pure S&P strategies. In truth, Allianz likewise has various charge choices that allow you to increase your exposure to their indexed alternatives.
Allianz is one of the very best IUL companies because of their diverse set of IUL investment optionsIt's worth noting that I've been an Allianz policyholder since 2014, and I can vouch for the fact that my IUL caps and participation rates aren't as competitive as what they have actually regularly provided on whatever their most current product is.
Life Insurance Options for Veterans
Therefore, it's vital to stress-test how Allianz's IUL policy holds up at lower crediting rates compared to the other leading Indexed Universal Life companies. A wide selection of unique indexes to choose fromRate-lock function when using the volatility control indexesAbility to be more aggressive with a 40% multiplier (for a 1% cost)Locked 5% loan rate to borrow against any of the indexed accountsTheir "Index Lock" only works with Volatility Control Indexes, not the pure S&P methods.
That in fact is why Nationwide is one of the leading IUL companies. Not only that, but they are a true mutual business, indicating they have no outside stockholders nor a holding company to siphon revenues to.

Latest Posts
Selecting the Top 2026 Medicare Supplement Coverage

Understanding PPO and HMO Medical Plans
Deciding Between PPO Vs HMO Health Plans